

⚓ Gosships Intelligence
Gosships Intelligence Is Published At Gosships.com
For Sponsorship And Partnership Inquiries Contact intelligence@gosships.com
|⚓ About Us | 🛢️ Exclusive Report | 📋 SwiftAction Training |
🏅Black Gold Membership (*53 Slots Left)
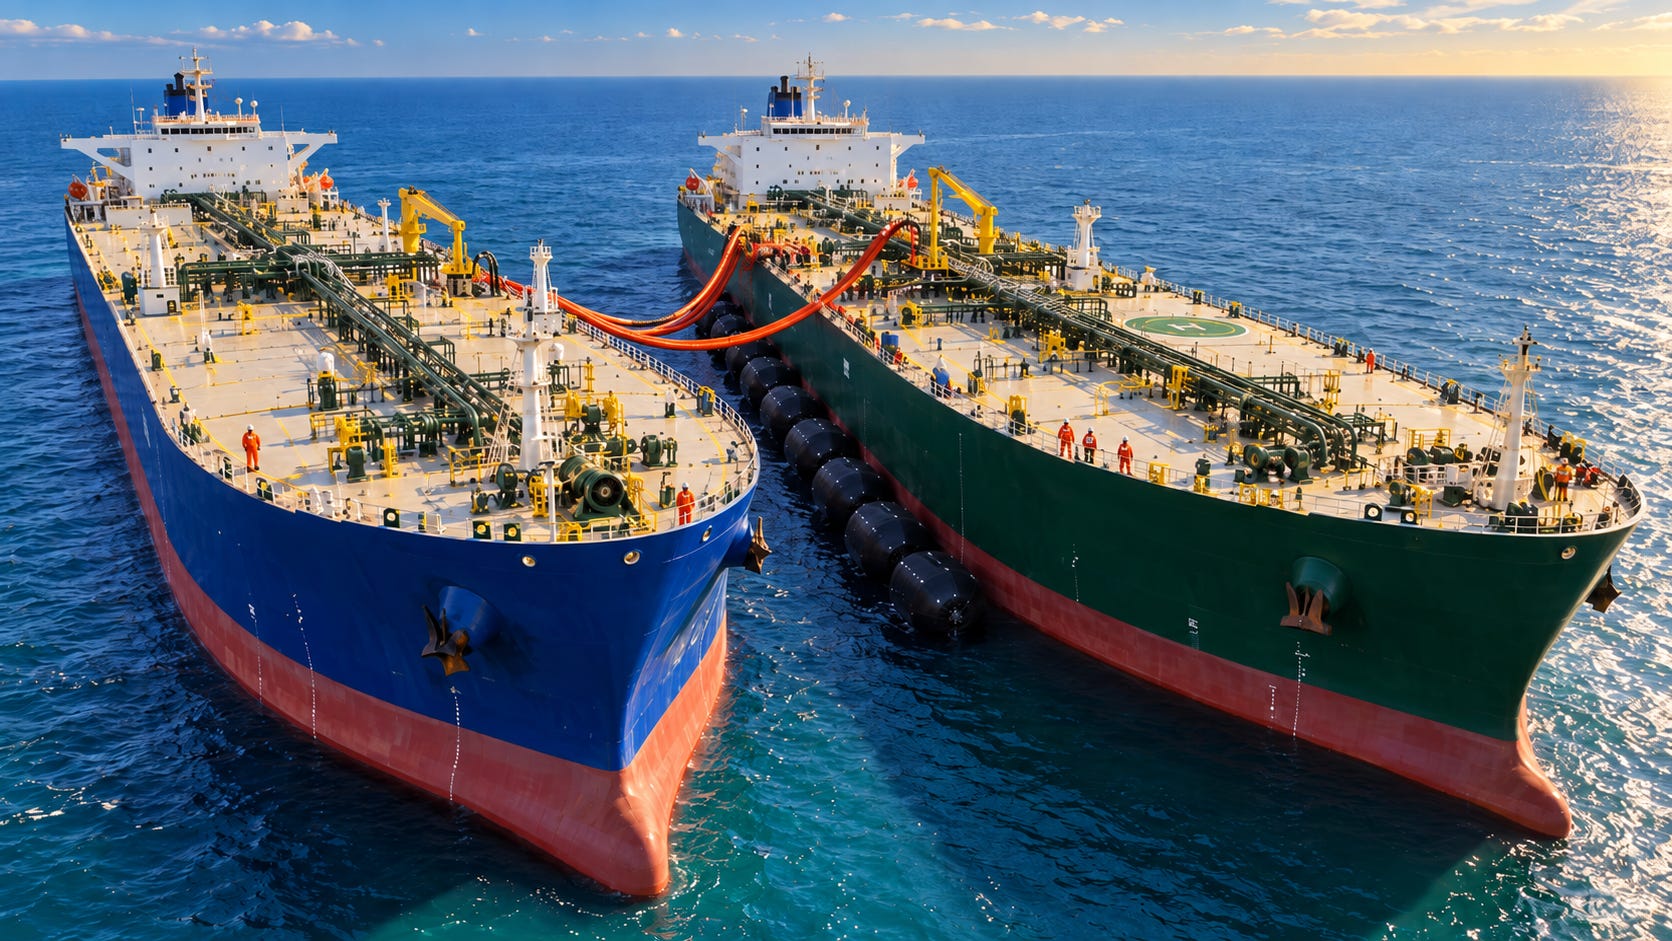
In the week to Thursday September 17 the Baltic Exchange assessed two crude routes out of the Middle East, and the gap between them says more than the record does. TD3C loads inside the Arabian Gulf and crosses the Strait of Hormuz, carrying the transit risk the market is pricing. TD34 loads at Mina Al Fahal out in the Gulf of Oman and crosses nothing at all. On this desk’s arithmetic from the exchange’s published assessments, TD3C rose 40.64 percent to a round trip equivalent of $1,212,503 a day. TD34 rose 86.99 percent to $870,947, and it gained more in absolute dollars doing it, $405,183 a day against $350,353. It also outran every other long haul crude route on the board: across the identical two Thursdays TD15 from West Africa to China rose 48.34 percent and TD22 from the US Gulf to China rose 51.13 percent. And the gap between the two Middle East legs did not widen as danger money should. It compressed, from $396,386 a day on September 10 to $341,556 on September 17, the ratio falling from 1.85 to 1.39. Nobody bids a route up 87 percent across two Thursdays to escape a danger that route has never carried. So the obvious reading of a record week, that the world has run out of VLCCs, is not what these prices are saying. The reason is physical. A barrel leaving the Arabian Gulf on the shuttle route now occupies two hulls where it used to occupy one. It is loaded inside the Gulf, carried across the strait on one vessel, transferred at sea off Fujairah or Sohar and carried on to Asia by a second vessel that, on Windward’s reading, typically never goes near the strait at all. Arsenio Longo of the maritime intelligence company Huax put it to AGBI on September 18. “The main point is that the long-haul tanker can stay outside Hormuz, but the oil still has to come through the strait on another ship.” Gibson Shipbrokers put a number on it the same day, writing that the combined VLCC count across the Arabian Gulf and the Gulf of Oman has lately exceeded the whole region’s supply before the war in January and February. More vessels than the region held before the war, while its exports sit far below pre-war levels even after the partial rebound Gibson itself measures at around 3.67 million barrels a day against the spring. The market is not short of vessels. It is short of what vessels do.
📋 In This Issue:
⚖️ The Story:
The two Baltic routes and the week they diverged, the spread that compressed while both rose, the five houses that described this before Gibson counted it, the two hull mechanism stated by Huax and Windward, the rival explanation that fits the same evidence and what any count built on tracking data physically cannot see
📊 By The Numbers:
The record print, the two routes and which one moved faster in percentage and in dollars, the spread that narrowed by $54,830 a day, the three commodity vessel transits through the strait and the distance a Chinese cargo no longer travels
🌍 Why It Matters:
What it changes for the owner with spot exposure, the charterer covering an Asian refinery, the marine underwriter writing the transit and the trader pricing the arbitrage
👀 What To Watch:
The pipeline restart estimates that run from days to eight weeks, the spread between the two routes, the transfer capacity at two anchorages and the falsifier that would break this brief outright
🚨 Gosships Signal:
Why a route that crosses nothing at all repricing faster than the route that crosses Hormuz is the number that settles what this market has actually been about


